- Who pays
- Every LLC registered with the SOS or doing business in California
- Amount
- $800 for taxable year 2026
- Due
- 15th day of the 4th month of the taxable year (April 15, 2026 for a calendar year)
- Filed with
- Franchise Tax Board, by mail with a check, or paid online without the voucher
- Form revision
- 2026, one page
At a glance
Form FTB 3522, LLC Tax Voucher, is the one-page Franchise Tax Board form that sends in the California limited liability company's $800 annual tax by check or money order. The top of the page holds the instructions; the voucher is the strip at the bottom, below the “DETACH HERE” line. This page follows the 2026 form, which pays the tax for taxable year 2026.
- Who uses it. “Every LLC that is doing business in California or that has articles of organization accepted or a certificate of registration issued by the SOS is subject to the $800 annual LLC tax.”
- When. By the 15th day of the 4th month after the LLC's taxable year begins: April 15, 2026 for a calendar-year LLC.
- How much. $800 for taxable year 2026 (FTB 3522, 2026; R&TC 17941(a), which ties the annual tax to the minimum franchise tax amount in R&TC 23153).
- How. Mail the voucher with a check or money order payable to the Franchise Tax Board, or pay online and skip the voucher.
- Not this form. The LLC fee for total California income of $250,000 or more goes on FTB 3536, and a corporation's minimum franchise tax is not paid on this LLC voucher.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
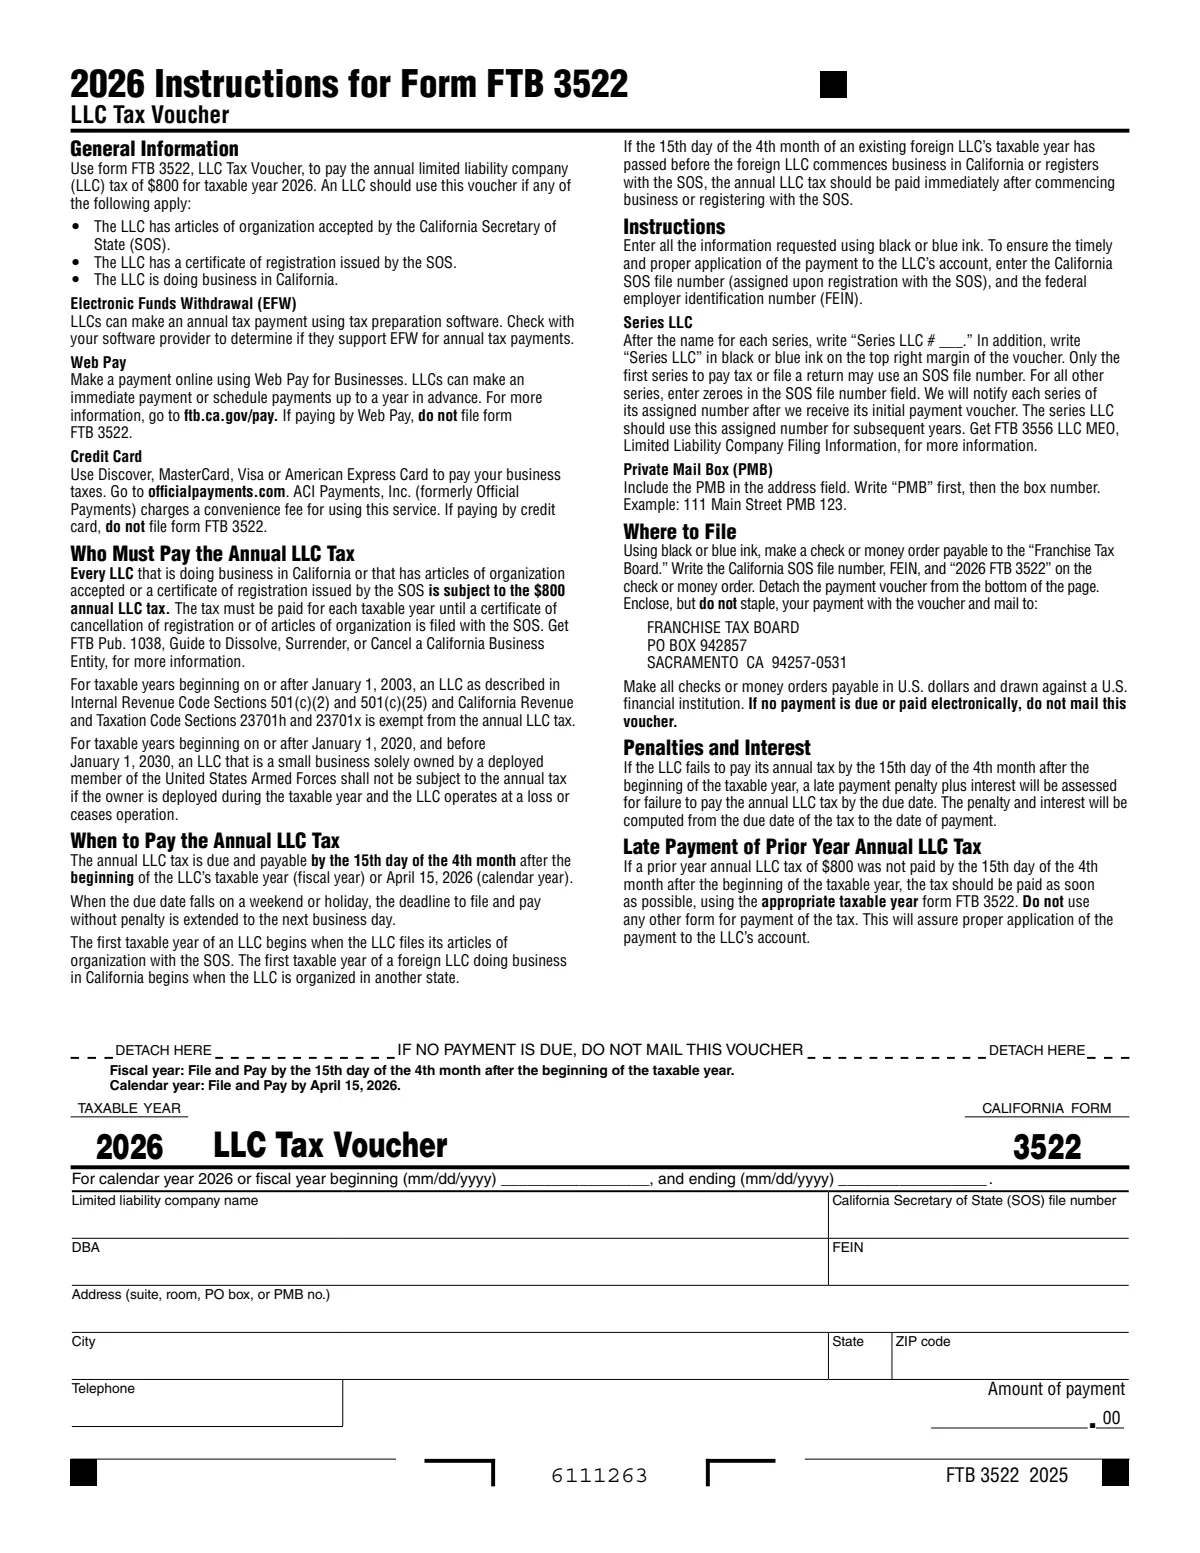
The voucher, line by line
The voucher has no numbered lines. Each row below matches a box on the image, top to bottom. The instructions ask for black or blue ink on every entry.
| Box | Label on the voucher | What goes there |
|---|---|---|
| Due | Fiscal year: File and Pay by the 15th day of the 4th month after the beginning of the taxable year. Calendar year: File and Pay by April 15, 2026. | “The annual LLC tax is due and payable by the 15th day of the 4th month after the beginning of the LLC’s taxable year (fiscal year) or April 15, 2026 (calendar year).” “When the due date falls on a weekend or holiday, the deadline to file and pay without penalty is extended to the next business day.” The clock starts when the taxable year begins, not when it ends: “The first taxable year of an LLC begins when the LLC files its articles of organization with the SOS. The first taxable year of a foreign LLC doing business in California begins when the LLC is organized in another state.” See when the tax is due below. |
| Series | Top right margin of the voucher | Only for a series LLC. The instructions say to write “Series LLC # ___” after the name of each series and to write Series LLC in black or blue ink on the top right margin of the voucher. Every other LLC leaves the margin blank. |
| Year | For calendar year 2026 or fiscal year beginning (mm/dd/yyyy) ____, and ending (mm/dd/yyyy) ____ | The 2026 voucher pays the tax for taxable year 2026. A calendar-year LLC needs no dates; a fiscal-year LLC writes the first and last day of its 2026 taxable year. A tax for an earlier year goes on that year's voucher: “the tax should be paid as soon as possible, using the appropriate taxable year form FTB 3522”. |
| Name | Limited liability company name | The name on the Secretary of State's record. A series LLC writes the series name followed by Series LLC # and its number. The free business search shows the exact name. |
| SOS | California Secretary of State (SOS) file number | The instructions ask for both numbers “to ensure the timely and proper application of the payment to the LLC’s account”: “enter the California SOS file number (assigned upon registration with the SOS), and the federal employer identification number (FEIN)”. Series LLCs: only the first series to pay tax or file a return may use an SOS file number. “For all other series, enter zeroes in the SOS file number field.” The FTB then sends each series its own number to use in later years. |
| DBA | DBA | The LLC's fictitious business name, if any. Leave it blank if the LLC uses only its legal name. |
| FEIN | FEIN | The LLC's nine-digit federal employer identification number, the same one it uses on Form 568. The instructions ask for it together with the SOS file number so the payment is applied to the LLC's account. |
| Address | Address (suite, room, PO box, or PMB no.) | “Include the PMB in the address field.” The instructions give the order: PMB first, then the box number, as in 111 Main Street PMB 123. |
| City | City / State / ZIP code | The city, state and ZIP code of the address on the line above. An LLC organized in another state uses its own mailing address; the voucher has no field for the state of organization. |
| Phone | Telephone | A daytime number for the person who handles the LLC's California payments. |
| Amount | Amount of payment | For taxable year 2026, $800 (FTB 3522, 2026). The cents are preprinted as .00, so the amount is whole dollars. “If no payment is due or paid electronically, do not mail this voucher.” Do not add the LLC fee here: the fee goes on FTB 3536, and the 2025 Form 568 booklet says “do not send the $800 annual tax with Form 568”. |
When the tax is due
The annual tax is paid in advance, at the start of the year it covers. The statute sets the date: the tax is “due and payable on or before the 15th day of the fourth month of the taxable year” (R&TC 17941(c)). For a calendar-year LLC that is April 15, 2026 on the 2026 voucher. A fiscal-year LLC counts from the first day of its own year.
A new LLC's first year starts on the day the articles are filed. The FTB's LLC page gives an example: an LLC that registers with the Secretary of State on June 18, 2020 owes its annual tax by September 15, 2020, the 15th day of the 4th month. Our example: an LLC whose articles are filed on February 10, 2026 counts February as month 1, so its first payment is due May 15, 2026.
A foreign LLC is different. Its first taxable year begins when it is organized in its home state, not when it registers in California. If that year's 4th month has already passed when it starts doing business in California or registers, “the annual LLC tax should be paid immediately after commencing business or registering with the SOS”.
FTB 3522 (2026) instructions; R&TC 17941(b) and (c); 2025 Form 568 Booklet, General Information.
The first year
The first-year rule has changed three times, and the 2026 voucher shows only the 2026 amount. Check which period the LLC's first taxable year falls in:
- First taxable year beginning in 2021, 2022 or 2023. No annual tax for the first taxable year (R&TC 17941(g)(1)(A)). The FTB's LLC page states it the same way for tax years beginning on or after January 1, 2021, and before January 1, 2024.
- First taxable year beginning in 2024, 2025 or 2026. The full $800. The statute has no first-year exception for these years, and the 2026 FTB 3522 shows $800 for taxable year 2026.
- First taxable year beginning in 2027, 2028 or 2029. “every limited liability company required to file a return under Section 18633.5 shall, instead of the amount specified in Section 23153, pay the annual tax to this state in the amount of four hundred dollars ($400) for its first taxable year” (R&TC 17941(g)(2), as amended by SB 180, effective July 13, 2026). Look for the 2027 FTB 3522 to show it; as of November 2026 the FTB's LLC page and the 2026 voucher still describe only the $800.
Two more ways out of the first year's tax. An LLC that cancels within a year of organizing can file the Secretary of State's short form cancellation (Form LLC-4/8), and the FTB says: “Your LLC will not be subject to the annual $800 tax for its first tax year.” And an LLC with a taxable year of 15 days or less that did no business in California in that year owes neither the tax nor the fee (R&TC 17946). The California franchise tax guide walks through each rule with its source.
Who pays and who does not
The tax follows the Secretary of State record, not activity. “The tax must be paid for each taxable year until a certificate of cancellation of registration or of articles of organization is filed with the SOS.” The FTB's LLC page puts it plainly: “This yearly tax will be due, even if you are not conducting business, until you cancel your LLC.” So an LLC that stopped operating but never filed a certificate of cancellation keeps owing $800 a year, and the unpaid years are what later block a revivor or a cancellation.
The instructions list the exceptions:
- Exempt title-holding LLCs. For taxable years beginning on or after January 1, 2003, “an LLC as described in Internal Revenue Code Sections 501(c)(2) and 501(c)(25) and California Revenue and Taxation Code Sections 23701h and 23701x is exempt from the annual LLC tax”.
- Deployed service members. For taxable years beginning on or after January 1, 2020, and before January 1, 2030, “an LLC that is a small business solely owned by a deployed member of the United States Armed Forces shall not be subject to the annual tax if the owner is deployed during the taxable year and the LLC operates at a loss or ceases operation”. The 2025 Form 568 booklet defines a small business for this rule as an LLC with $250,000 or less of total income from California sources.
- LLCs taxed as corporations. The annual LLC tax applies to an LLC “that is not taxable as a corporation for California tax purposes” (R&TC 17941(d)). An LLC that elected corporate treatment follows the corporation rules instead.
Paying, with or without the voucher
The voucher is only for paper payments. Online payments replace it:
- Web Pay. The FTB's Web Pay for Businesses takes an immediate payment or schedules one up to a year ahead. “If paying by Web Pay, do not file form FTB 3522.”
- Credit card. Accepted through the card payment service named in the instructions, which charges a convenience fee. Do not file the voucher after a card payment either.
- Electronic funds withdrawal. Some tax preparation software can withdraw the annual tax payment; the instructions say to check with the software provider.
- Check or money order. Payable to the Franchise Tax Board, in U.S. dollars, drawn on a U.S. financial institution. “Write the California SOS file number, FEIN, and “2026 FTB 3522” on the check or money order.” Detach the voucher from the bottom of the page. The instructions say: “Enclose, but do not staple, your payment with the voucher”. Mail both to Franchise Tax Board, PO Box 942857, Sacramento CA 94257-0531, the address printed in the 2026 instructions.
The FTB's LLC page lists the same PO box with a different ZIP+4 (94257-0631) for annual tax payments by mail. The voucher's own instructions give 94257-0531; follow the form you are mailing.
FTB 3522 and FTB 3536 (2026) instructions; FTB LLC page (updated March 5, 2026); 2025 Form 568 Booklet.
Late or missed payments
The instructions spell out what happens when the 15th day of the 4th month passes without payment: “a late payment penalty plus interest will be assessed for failure to pay the annual LLC tax by the due date”. The penalty and interest run from the tax's due date to the day it is paid. The 2025 Form 568 booklet explains the penalty: “The failure-to-pay penalty begins at 5%.” It grows by 0.5% for each month or part of a month the tax stays unpaid, up to 25% after 40 months, and the booklet notes that for the annual tax the penalty is figured from the 15th day of the 4th month, not from the return's due date.
Paying an old year late? Use that year's voucher, not the current one: “the tax should be paid as soon as possible, using the appropriate taxable year form FTB 3522”. The instructions add that no other form should be used, so the payment is applied to the right year.
The bigger risk is status. The booklet's suspension note reads: “LLCs are suspended or forfeited for failure to file or failure to pay.” A suspended LLC is not in good standing and cannot do business in California until it is revived with FTB 3557 LLC (the corporation version is FTB 3557 BC). The California suspension and revivor guide covers the steps.
How it connects
- Form 568. The annual tax is reported again on the LLC's return: the 2025 booklet tells LLCs to enter the $800 on Form 568, line 3, and the amount paid with FTB 3522, FTB 3536 and FTB 3537 on line 8. The return itself does not carry the $800 payment.
- FTB 3536. The LLC fee is a separate payment on a separate form, due two months later: FTB 3536 line by line.
- The numbers. The California LLC fee calculator gives the annual tax and the fee tier for a year.
- The rules. California franchise tax: $800 minimum tax and LLC fee, and the multistate view in franchise and privilege taxes.
- The other filing. Paying the tax does not keep an LLC in good standing by itself: it also files a Statement of Information with the Secretary of State every two years (Form LLC-12). See the California Statement of Information guide and the California good standing page.
Common mistakes
- Paying the $800 with the return. The tax is due in the 4th month of the year it covers, a year before most LLCs file that year's Form 568. The booklet says not to send it with the return.
- Using this year's voucher for last year's tax. Each year has its own FTB 3522. A late 2025 payment goes on the 2025 voucher.
- Leaving out the SOS file number or FEIN. They are how the FTB finds the LLC's account. Write both on the check as well.
- Mailing the voucher after paying online. If the LLC paid by Web Pay, card or software withdrawal, there is nothing to mail.
- Thinking an idle LLC owes nothing. The tax is owed every year until the LLC files a certificate of cancellation with the Secretary of State.
- Counting from the end of the year. The return is due after the year ends; the annual tax is due near its start.
Questions filers ask
Is the $800 due if the LLC made no money?
Yes. The tax is owed for each taxable year in which the LLC is registered with the Secretary of State or doing business in California, until it files a certificate of cancellation. Income only matters for the separate LLC fee, which starts at $250,000 of total California income.
When is the first payment due for a new California LLC?
By the 15th day of the 4th month after the articles are filed, because that is when the first taxable year begins. For a first taxable year beginning in 2024 to 2026 it is the full $800; for one beginning in 2027 to 2029, R&TC 17941(g)(2) sets $400.
Can I pay FTB 3522 online?
Yes. Web Pay for Businesses, a credit card payment or an electronic funds withdrawal through tax software all work, and the instructions say not to file the voucher after an online payment.
We paid the tax late. Which voucher do we use?
The voucher for the taxable year the tax belongs to. The 2026 instructions say a late prior-year tax should be paid as soon as possible using the appropriate taxable year form FTB 3522, and no other form.
Does a foreign LLC registered in California pay the $800?
Yes, once it registers with the Secretary of State or does business in California. Its first taxable year starts when it was organized at home, so if the 4th month has passed when it registers, the instructions say to pay immediately.
Does an LLC taxed as an S corporation use FTB 3522?
No. The annual LLC tax applies to an LLC that is not taxable as a corporation for California purposes (R&TC 17941(d)). An LLC taxed as a corporation follows the corporation franchise tax rules.