- Who pays
- LLCs with total California income of $250,000 or more
- Amount
- $900, $2,500, $6,000 or $11,790 (2026)
- Due
- 15th day of the 6th month of the taxable year (June 15, 2026 for a calendar year)
- Filed with
- Franchise Tax Board, by mail with a check, or paid online without the form
- Form revision
- 2026, one page
At a glance
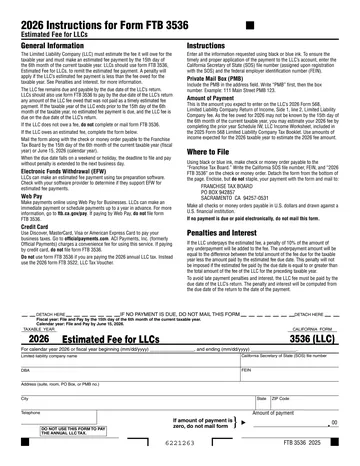
Form FTB 3536, Estimated Fee for LLCs, sends a California LLC's estimated LLC fee to the Franchise Tax Board in the middle of the year the fee is for. The LLC fee is separate from the $800 annual tax: it applies only when the LLC's total income from California sources reaches $250,000, and it rises in four steps to $11,790. Like FTB 3522, the 2026 form is one page with the instructions on top and the payment form below the detach line.
- Who uses it. An LLC subject to the annual tax that expects total California income of $250,000 or more for the year (R&TC 17942(a)). An LLC below that line owes no fee and files no FTB 3536.
- When. By the 15th day of the 6th month of the current taxable year: June 15, 2026 for a calendar-year LLC. Any balance is paid on the same form by the return's due date.
- How much. $900, $2,500, $6,000 or $11,790 for 2026, by income tier (R&TC 17942(a); FTB LLC page).
- How. Mail the form with a check or money order to Franchise Tax Board, PO Box 942857, Sacramento CA 94257-0531, or pay online and skip the form.
- Penalty. 10% of an underpayment, unless the estimate paid on time equals at least last year's fee.
Tap a box once for its note, again to jump to the line. Zoom in to read the small print.
The form, line by line
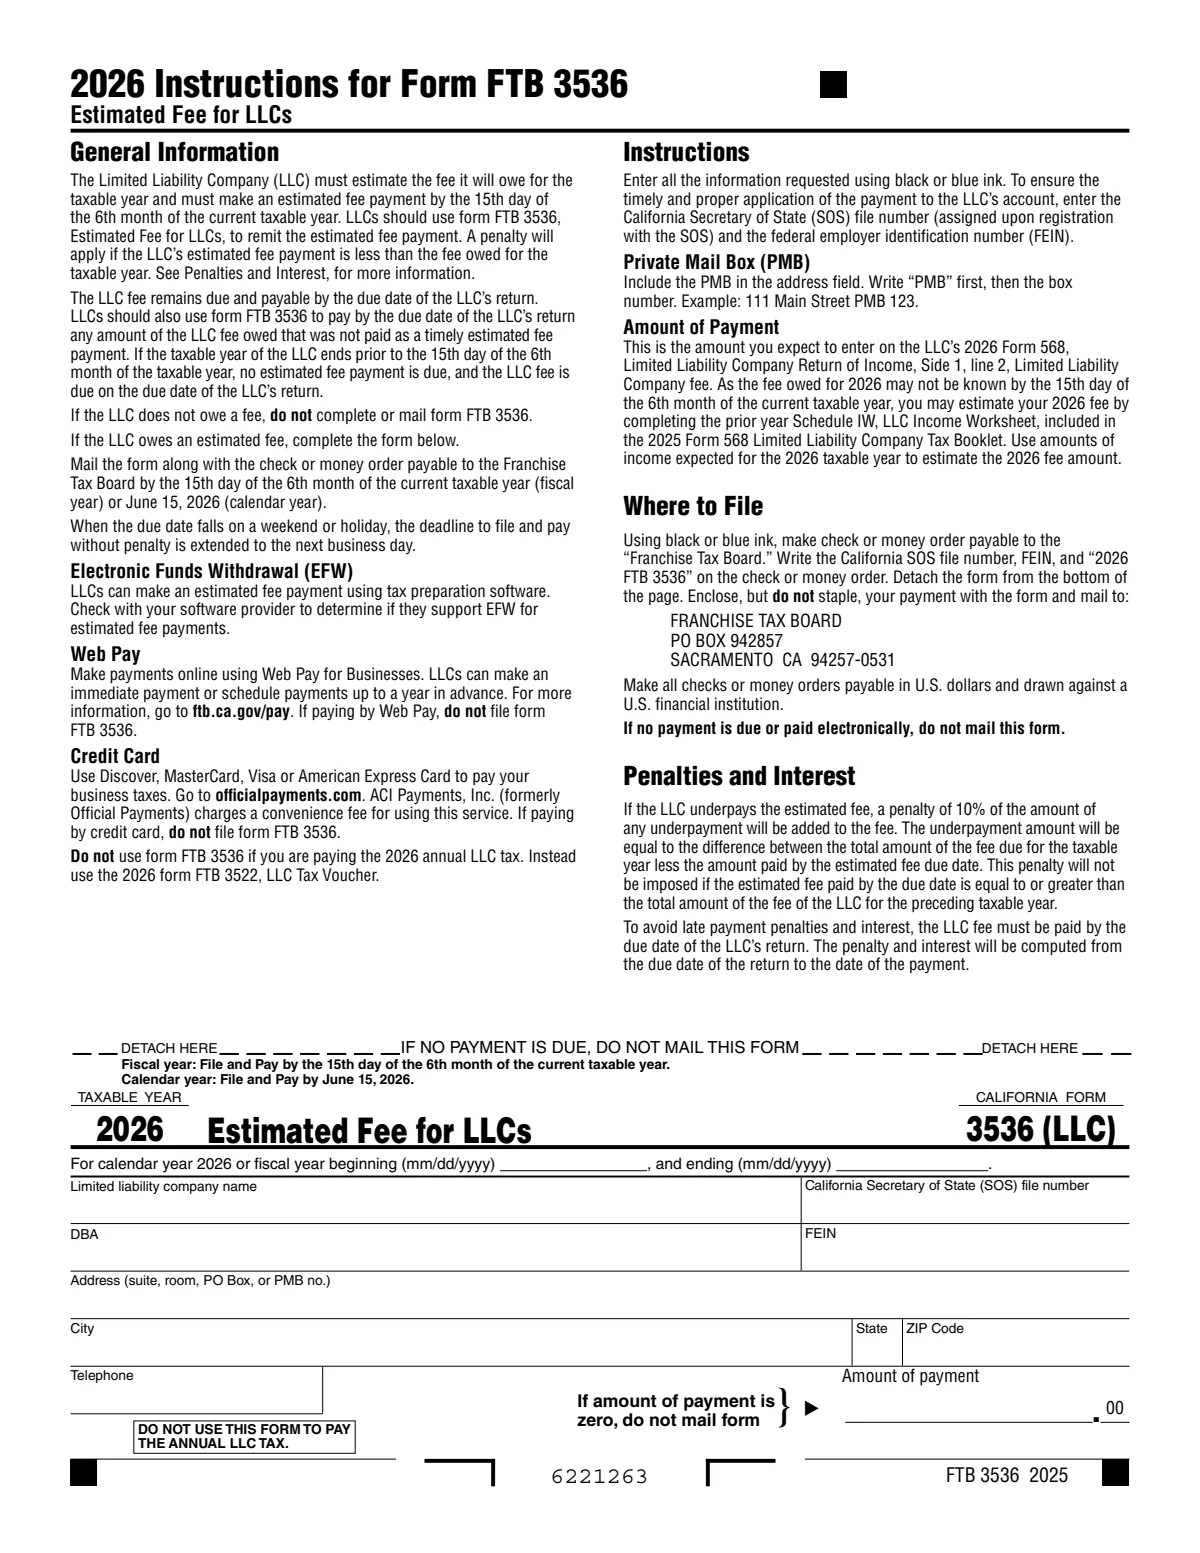
The payment form has no numbered lines. Each row below matches a box on the image, top to bottom. The instructions ask for black or blue ink.
| Box | Label on the form | What goes there |
|---|---|---|
| Due | Fiscal year: File and Pay by the 15th day of the 6th month of the current taxable year. Calendar year: File and Pay by June 15, 2026. | “The Limited Liability Company (LLC) must estimate the fee it will owe for the taxable year and must make an estimated fee payment by the 15th day of the 6th month of the current taxable year.” The statute uses the same words: the fee “shall be estimated and paid on or before the 15th day of the sixth month of the current taxable year” (R&TC 17942(d)(1)). Weekend and holiday dates move to the next business day. “If the taxable year of the LLC ends prior to the 15th day of the 6th month of the taxable year, no estimated fee payment is due, and the LLC fee is due on the due date of the LLC’s return.” |
| Year | For calendar year 2026 or fiscal year beginning (mm/dd/yyyy) ____, and ending (mm/dd/yyyy) ____ | The 2026 form carries the fee for taxable year 2026. A fiscal-year LLC writes the first and last day of its 2026 taxable year; a calendar-year LLC needs no dates. |
| Name | Limited liability company name | The name on the Secretary of State's record, the same name as on FTB 3522 and Form 568. |
| SOS | California Secretary of State (SOS) file number | The instructions ask the LLC to “enter the California Secretary of State (SOS) file number (assigned upon registration with the SOS) and the federal employer identification number (FEIN)”, so the payment reaches the right account. |
| DBA | DBA | The LLC's fictitious business name, if any. |
| FEIN | FEIN | The LLC's federal employer identification number. Write it, the SOS file number and “2026 FTB 3536” on the check as well. |
| Address | Address (suite, room, PO Box, or PMB no.) | “Include the PMB in the address field.” Write PMB first, then the box number. |
| City | City / State / ZIP Code | The city, state and ZIP code of the address above. |
| Phone | Telephone | A daytime number for the person who handles the LLC's California payments. |
| Not-tax | DO NOT USE THIS FORM TO PAY THE ANNUAL LLC TAX. | “Do not use form FTB 3536 if you are paying the 2026 annual LLC tax.” The $800 annual tax goes on FTB 3522, two months earlier. Each payment has its own form so it is applied to the right liability. |
| Zero | If amount of payment is zero, do not mail form | “If the LLC does not owe a fee, do not complete or mail form FTB 3536.” No fee is owed when total California income is under $250,000 (R&TC 17942(a)(1)). |
| Amount | Amount of payment | “This is the amount you expect to enter on the LLC’s 2026 Form 568, Limited Liability Company Return of Income, Side 1, line 2, Limited Liability Company fee.” The fee is not known yet in the 6th month, so the instructions allow an estimate: “you may estimate your 2026 fee by completing the prior year Schedule IW, LLC Income Worksheet, included in the 2025 Form 568 Limited Liability Company Tax Booklet.” “Use amounts of income expected for the 2026 taxable year to estimate the 2026 fee amount.” Pick the tier from the table below and enter that dollar amount; the cents are preprinted. |
FTB 3522 and FTB 3536 (2026); R&TC 17942(c) and (d); 2025 Form 568 Booklet. A multi-member LLC's return is due the 15th day of the 3rd month after the year ends (March 15, 2027 here, our example).
Which tier, and what counts as income
The fee is a flat amount per tier, not a percentage. The tier depends on “total income from all sources derived from or attributable to this state for the taxable year” (R&TC 17942(a)). The FTB's LLC page states the chart this way: “If the total California income rounded to the nearest whole dollar is:”
R&TC 17942(a); FTB LLC page fee chart (updated March 5, 2026). Under $250,000: no fee and no FTB 3536.
“Total income” is broader than profit. The statute defines it as “gross income, as defined in Section 24271, plus the cost of goods sold that are paid or incurred in connection with the trade or business of the taxpayer” (R&TC 17942(b)(1)(A)). Adding cost of goods sold back to gross income brings the figure close to total receipts, so an LLC with $600,000 of California sales and a loss for the year still lands in the $2,500 tier (our example). Income is assigned to California with the sales factor rules, so a multistate LLC counts only its California-sourced amounts (R&TC 17942(b)(1)(B)). Allocations an LLC receives as a member of another LLC whose income is already subject to the fee are left out. The 2025 Form 568 booklet carries the figure from Schedule IW, line 17, to Form 568, line 1.
Splitting one business into several LLCs to stay under a tier does not work if the FTB finds the purpose was the fee. The FTB may combine the total income of commonly controlled LLCs “if it determines that multiple limited liability companies were formed for the primary purpose of reducing fees payable under this section”, and each of them is then jointly and severally liable for the fee (R&TC 17942(b)(2)).
Estimating the fee
By the 6th month the year is only half over, so the amount on the form is a forecast. The instructions give the method: “you may estimate your 2026 fee by completing the prior year Schedule IW, LLC Income Worksheet, included in the 2025 Form 568 Limited Liability Company Tax Booklet.” “Use amounts of income expected for the 2026 taxable year to estimate the 2026 fee amount.” In practice, take the income the LLC expects for the full year, find the tier and enter that tier's fee. The California LLC fee calculator does the lookup.
A short first or last year changes the timing. “If the taxable year of the LLC ends prior to the 15th day of the 6th month of the taxable year, no estimated fee payment is due, and the LLC fee is due on the due date of the LLC’s return.” And an LLC whose taxable year was 15 days or less, with no business in California in that time, owes neither the tax nor the fee (R&TC 17946).
The 10% penalty and the safe harbor
“If the LLC underpays the estimated fee, a penalty of 10% of the amount of any underpayment will be added to the fee.” The underpayment is the year's total fee minus what was paid by the estimate's due date (R&TC 17942(d)(2)). “This penalty will not be imposed if the estimated fee paid by the due date is equal to or greater than the total amount of the fee of the LLC for the preceding taxable year.”
That safe harbor is the planning tool. An LLC that paid $2,500 last year and pays at least $2,500 by June 15 owes no 10% penalty even if the year lands in the $6,000 tier; it pays the $3,500 difference by the return's due date (our example). An LLC whose income jumps in its first fee year has no prior-year fee to lean on, so its estimate has to be right.
Paying the balance
“The LLC fee remains due and payable by the due date of the LLC’s return.” “LLCs should also use form FTB 3536 to pay by the due date of the LLC’s return any amount of the LLC fee owed that was not paid as a timely estimated fee payment.” That second use of the form is easy to miss: the balance is not paid with Form 568 itself but on FTB 3536, by the original due date of the return. “To avoid late payment penalties and interest, the LLC fee must be paid by the due date of the LLC’s return.”
The return's due date depends on how the LLC is classified. “For LLCs classified as partnerships, the original due date of the return is the 15th day of the 3rd month following the close of the taxable year.” A single-member LLC owned by an S corporation, a partnership or another LLC classified as a partnership has the same date; any other single-member LLC files by the 15th day of the 4th month after its owner's year closes (2025 Form 568 Booklet). An extension to file does not help with the fee: “However, the automatic extension does not extend the time to pay the LLC fee or nonconsenting nonresident members’ tax.” Paying after the return's due date brings the late payment penalty and interest on top of any 10% underpayment penalty.
Paying, with or without the form
The form is only for paper payments. Web Pay for Businesses takes an immediate or scheduled payment, a credit card payment goes through the service named in the instructions (it charges a convenience fee), and some tax software can make an electronic funds withdrawal. “If no payment is due or paid electronically, do not mail this form.” For a paper payment, make the check or money order payable to the Franchise Tax Board in U.S. dollars. “Write the California SOS file number, FEIN, and “2026 FTB 3536” on the check or money order.” Detach the form, enclose the payment without stapling it, and mail both to the PO box above.
How it connects
- FTB 3522. The $800 annual tax is due two months earlier on its own voucher: FTB 3522 line by line.
- Form 568. The fee is figured on the return (line 1 total California income from Schedule IW, line 2 the fee), and the amounts paid with FTB 3522, FTB 3536 and FTB 3537 go on line 8 (2025 Form 568 Booklet).
- The rules. California franchise tax: $800 minimum tax and LLC fee and franchise and privilege taxes across the states.
- Status. An unpaid fee is collected like a tax and can lead to suspension, which the California suspension and revivor guide explains. The California good standing page has the full picture.
Common mistakes
- Sending the $800 on FTB 3536. The form says in capitals not to use it for the annual tax.
- Measuring net income. The tier is set by total California income, gross income plus cost of goods sold, not by profit.
- Skipping the estimate because the year is uncertain. Paying at least last year's fee by the 6th month avoids the 10% penalty whatever the year brings.
- Waiting for the extended return date. The fee balance is due by the original due date even when the return is on extension.
- Paying the balance with the return. The instructions route the balance through FTB 3536 as well.
Questions filers ask
Do I need to file FTB 3536 if my LLC made less than $250,000?
No. The fee starts at $250,000 of total California income, and the instructions say that if the LLC does not owe a fee, do not complete or mail form FTB 3536.
Is the LLC fee based on profit or revenue?
Neither exactly. It is based on total income from California sources: gross income plus the cost of goods sold (R&TC 17942(b)(1)(A)). For most operating businesses that is close to California gross receipts.
What if my estimate is too low?
A penalty of 10% of the underpayment is added to the fee, unless the amount paid by the 15th day of the 6th month was at least the LLC's total fee for the year before. Pay the remaining fee on FTB 3536 by the return's due date.
Does the extension to file Form 568 give more time to pay the fee?
No. The 2025 Form 568 booklet says the automatic extension does not extend the time to pay the LLC fee.
Can a new LLC skip the estimate in its first year?
Only if its taxable year ends before the 15th day of the 6th month; then no estimated payment is due and the fee is due with the return. Otherwise the estimate is due, and there is no prior-year fee to use as a safe harbor.
Can I pay FTB 3536 online?
Yes. Web Pay for Businesses, a credit card or an electronic funds withdrawal through tax software all work, and the instructions say not to file the form after paying online.